
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Some links on this page are affiliate links: if you buy through them we may earn a commission, at no extra cost to you.
Pet insurance shifts part of the risk of eligible veterinary bills to an insurer; paying out of pocket means keeping that risk yourself. Neither option is automatically cheaper over a pet’s lifetime. Insurance can help with a large covered expense, but most policies reimburse you after you pay the clinic, so you may still need cash or credit up front. The right choice depends on the actual policy and quote, your pet’s health and age, local veterinary costs, and how much you can comfortably keep available for care.
At a glance
| Name | Best for | Key difference | Checked |
|---|---|---|---|
| Pet insurance | Owners who want to transfer some eligible high-cost risk and can manage premiums and policy cost sharing | Premiums buy reimbursement for eligible care, subject to the contract’s deductible, reimbursement calculation, limits, waiting periods, and exclusions | November 2026 |
| Paying veterinary bills out of pocket | Owners who prefer not to pay premiums and can fund routine care and a potentially large unexpected bill | You keep the savings you would have spent on premiums, but you are responsible for the full bill | November 2026 |
What is the real difference between pet insurance and paying out of pocket?
It is a choice between paying a recurring premium to transfer some eligible costs and retaining the full veterinary-cost risk yourself. Insurance is not a promise that every bill will be paid, and a premium is not the amount the insurer will eventually contribute. Deductibles, reimbursement rules, limits, waiting periods, and exclusions all affect the result.
As an Amazon Associate I earn from qualifying purchases.
Self-funding is not the same as having no plan. It means setting aside accessible money for veterinary care and accepting that you may need to pay a large bill from those funds. If the bill exceeds what you have saved, you remain responsible for the balance. Insurance can reduce some eligible costs, but it may not solve an immediate cash-flow problem: most pet policies reimburse after the owner pays the clinic and submits a claim. Some direct-payment arrangements may be available, so confirm the arrangement with both the insurer and the veterinary clinic before relying on it.
There is no evidence establishing which option costs less across pets’ lifetimes. Average premiums are not a forecast of one pet’s claims, and they do not establish a break-even age or guaranteed savings. The useful comparison is between an actual quote and policy, on one side, and your ability and willingness to pay bills yourself, on the other.
Popular on Amazon

- Dog multivitamins chewable for skin & coat : Dog multivitamin is rich in Omega-3 fatty acids and vitamin E,which can relieve skin allergies,dryness,itching and other problems.Multivitamin for dogs nourishes skin follicles.Long-term consumption of dog vitamins multivitamin can make dog hair stronger and smoother,and reduce coat loss.The COQ10 in dog multivitamin chewable can resist oxidation and delay cell aging.Dogs with skin injuries can eat dog vitamins and supplements to promote wound healing
- Dog multivitamin relieves joint inflammation: Dog vitamins for hip and joint can supplement high-quality MSM, glucosamine, and chondroitin sulfate to promote cartilage development and repair. Long-term consumption of dog multivitamins chewable can enhance the elasticity and toughness of joint cartilage, improve joint flexibility, and move more freely. Dog multivitamin chews can reduce joint friction and relieve joint pain. Dog vitamins and supplements can prevent and improve dog joint problems
- Dog multivitamin chews are good for the gut: Vet-endorsed formula dog vitamins and supplements made from natural ingredients.Dog vitamins multivitamin chewables contain a rich blend of probiotics to support intestinal and digestive health.Dog vitamins for small dogs can regulate the balance of intestinal flora,help calcium absorption,and promote bone development.Dog multivitamins chewables improve energy metabolism,converting food into energy, making dogs more energetic in their daily activities
- Dog multivitamin chews protect overall health:Senior dog vitamins and supplements help improve blood circulation and prevent cardiovascular disease.Dog multivitamins chewable support normal liver function,promote liver detoxification,and improve negative mood.For dog with heart problems and older dog,taking dog vitamins and supplements in moderation is an auxiliary health care measure.Dog vitamins multivitamin helps enhance white blood cell activity,improve immunity,prevent infection and disease
- Dog multivitamins chewable promote brain development: The DHA in krill oil in multivitamin for dogs is an important component of the brain and retina. Dog vitamins and supplements can improve dog cognitive ability. When training puppies to learn basic commands, puppies who are properly supplemented with dog vitamins multivitamin will behave more intelligently and improve memory.Dog supplements & vitamins can prevent and relieve eye problems such as dry eyes and tear stains, and keep eyes healthy
How much does pet insurance cost on average?
The latest figures are U.S. averages for 2025, reported by the North American Pet Health Insurance Association (NAPHIA) in its 2026 State of the Industry report. They are useful as a dated market benchmark, not as a quote or a prediction of the cost for a particular pet.
| Coverage type | Dogs: average per year | Cats: average per year |
|---|---|---|
| Accident and illness | $836 | $435 |
| Accident only | $190 | $112 |
| Coverage with embedded wellness | $1,414 | $859 |
Prices checked November 2026; figures are 2025 U.S. weighted averages reported by NAPHIA’s 2026 State of the Industry report highlights.
NAPHIA says the report reflects calendar year 2025, was published in June 2026, and estimates its data represents approximately 99% of written pet-health-insurance premium in the United States and Canada. NAPHIA is an industry association; its reported averages describe market data, not the price you will be offered or how much your pet will cost to insure. Your quote can differ based on factors including the pet’s breed, age, spay or neuter status, prior claims, selected coverage limits, deductible, copay, and coinsurance. Premiums may also change from year to year and may rise as a pet ages, according to the Pennsylvania Insurance Department’s pet insurance guidance.
The wellness figure is not directly interchangeable with the accident-and-illness figure: it represents coverage with wellness benefits embedded. Routine preventive care may be optional or included in some plans, often at additional cost. Check what the plan actually covers before comparing its price with a policy that does not include those benefits.
Also popular on Amazon

- Joint Health Supplement for Dogs: Cosequin is the #1 vet recommended retail joint health supplement brand, supporting joint health in dogs for over 25 years
- Contains Glucosamine for Dogs: Cosequin contains glucosamine hydrochloride (FCHG49) and sodium chondroitin sulfate (TRH122), plus methylsulfonylmethane (MSM). This unique combination of ingredients supports healthy joints
- For Any Breed or Size: Whether you have a young or senior dog, a small or large breed, Cosequin helps support their joint health
- Tasty Chews for Daily Use: Cosequin comes in a tasty chewable tablet, making daily administration easy and convenient
- Exceptional Quality: Cosequin is backed by science, undergoing thorough quality inspections to ensure your dog receives a safe, high-quality product. It is manufactured in the United States with globally sourced ingredients
What does pet insurance cover—and what might it leave you paying?
Start with the policy category, then check the contract’s specific covered treatments and exclusions. Accident-only plans generally focus on injuries or illnesses caused by mishaps; accident-and-illness plans add illness coverage. Neither label alone tells you whether a particular appointment, treatment, fee, or condition qualifies.
- Accidents versus illness: An accident-only policy is narrower than accident-and-illness coverage. If you are comparing them, identify the kinds of care each contract treats as an accident or illness.
- Routine and preventive care: Do not assume annual checkups, vaccines, or other preventive services are included in a standard accident-and-illness policy. Look for a clearly described wellness benefit and determine whether it is optional or included.
- Exam fees, prescriptions, and other charges: Check whether the contract covers each category of expense you expect to claim. A condition being covered does not necessarily mean every related charge is reimbursable.
- Hereditary and congenital conditions: These may be excluded or limited. Review the policy’s definitions and restrictions, particularly if your pet’s history or breed makes such terms relevant.
- Pre-existing conditions: These are rarely covered. A condition noted in veterinary records before enrollment may affect eligibility, depending on the insurer’s definition and contract. The Pennsylvania Insurance Department puts the timing point plainly: “Pre-existing conditions are rarely covered, so the time to buy a plan is before your pet gets sick or hurt.”
Buying earlier may preserve the possibility of coverage for future eligible care, but it does not make every future condition covered. Waiting periods still apply, and policy definitions, exclusions, and other terms govern. The National Association of Insurance Commissioners’ overview of pet insurance coverage describes these general policy features; its report is from 2019, so use it for mechanics and regulatory context rather than current prices or a census of today’s insurers.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsHow much of a covered bill would insurance actually reimburse?
Estimate the insurer’s share from the contract’s calculation, not from the premium or a headline reimbursement percentage. A covered bill can still leave you paying a deductible, your share of eligible costs, amounts above a limit, and any expenses the policy excludes.
Read these policy terms together:
- Deductible: Find out how much you must pay before reimbursement begins and how the deductible applies. Policies can differ in the way they structure deductibles.
- Reimbursement percentage or benefit schedule: A reimbursement percentage is only one part of the calculation. Some policies use a benefit schedule or another method to determine the eligible amount, so check how the plan calculates a claim rather than assuming the percentage applies to the entire invoice.
- Copay or coinsurance: Identify the portion of eligible expenses that remains your responsibility after the deductible, and whether the contract uses a copay, coinsurance, or both.
- Coverage limits: Check whether benefits have an annual, lifetime, per-condition, per-procedure, per-incident, or combined maximum. A limit can cap reimbursement even when a treatment would otherwise be eligible.
- Waiting periods and exclusions: Check when coverage starts and which conditions or expenses are excluded. A bill arising during a waiting period or for an excluded condition may not be reimbursed.
For example, a plan’s stated reimbursement level does not mean you receive that share of every dollar on a clinic invoice. The deductible may apply first; the insurer may calculate eligible costs under a benefit schedule; your coinsurance may remain; and a limit or exclusion may further reduce what is paid. The exact calculation depends on the contract. The NAIC describes deductibles, benefit calculations, limits, waiting periods, and exclusions as common policy features, but the terms of the individual policy—not a generic label—determine your result.
Also popular on Amazon
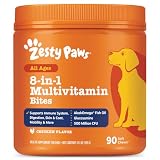
- 8-in-1 Formula - Zesty Paws Multifunctional Bites are functional supplement chews with premium ingredients that support physical performance, antioxidants, hip & joint, heart, immune, skin, liver, & gut health for dogs of all ages, breeds, and sizes.
- Skin Health & Antioxidants – For animals with sensitive skin, this formula contains Cod Liver Fish Oil and Vitamin E to help maintain normal moisture and CoQ10 to help reduce oxidative stress.
- Hip, Joint & Performance Support - Each dog chew features OptiMSM, a premium form of MSM for muscular support, which works synergistically with the Glucosamine HCl and Chondroitin Sulfate in these chews for hip and joint support plus Cod Liver Oil and B-Complex Vitamins support normal physical performance.
- Gut Health & Probiotics - These chews also contain a six-strain Gut Health Blend (500 million cfu per chew) and a Digestive Health Blend to promote gut flora while supporting normal bowel function for dogs.
- Heart, Liver & Immune Health - Multifunctional Bites feature powerful antioxidants, premium CoQ10, Cod Liver Oil and Vitamins A, C, & E to promote healthy cardiovascular function, support liver health and enhance immune response.
Will you have to pay the veterinarian before insurance pays?
Usually, yes: most pet insurance works by reimbursement. You pay the veterinarian, submit a claim with supporting records and itemized receipts, and the insurer reimburses the covered amount according to the policy. The Hawaii Insurance Division’s pet insurance FAQs describe this typical claims sequence and note that most veterinarians do not bill insurers directly.
This matters even if you expect a claim to be covered. You may need to cover the full invoice while the claim is reviewed, and you may ultimately be responsible for the deductible, cost sharing, excluded expenses, or amounts over a limit. Ask the insurer how to submit a claim and what documentation it requires; confirm with the clinic whether it can work with any direct-pay arrangement the insurer offers. Do not assume direct payment is available simply because a policy reimburses eligible expenses.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →How should you compare a quote with self-funding?
Use a real quote and the complete policy wording, then compare them with the savings you can actually access. The goal is not to predict every future vet bill; it is to decide whether the cost and terms of transferring part of the risk are worth it to you.
- Get a quote for the pet and coverage you want. Compare the annual premium, not just the first monthly payment. Ask how premiums may change over time and whether the quote reflects the deductible, reimbursement method, and limits you would choose.
- Read the exclusions and eligibility rules before focusing on price. Check pre-existing-condition definitions, waiting periods, age restrictions, hereditary or congenital limitations, and any conditions in the pet’s veterinary records that could affect coverage.
- Map the policy to likely expenses. Check accident and illness coverage, routine-care or wellness benefits, exam fees, prescriptions, and other expense categories relevant to the plan. Confirm which are covered, optional, limited, or excluded.
- Work through a large-claim scenario using the contract. Apply the deductible, reimbursement calculation, cost sharing, and benefit limits to an example bill. This is not a claim forecast; it helps reveal what portion could remain yours if a covered expense occurs.
- Check the payment sequence. Determine whether you would need to pay the clinic first, what claim records are required, and whether the insurer and clinic can confirm any direct-payment option.
- Compare against accessible savings, not an abstract emergency fund. Ask whether you could continue paying for routine care while retaining enough readily available money for an unexpected bill. There is no universal savings threshold; the relevant amount depends on your circumstances and local veterinary costs.
- Decide which risk you would rather carry. Insurance means recurring premiums plus any costs the policy leaves to you. Self-funding means no premiums, but full responsibility for bills. Choose based on your budget, risk tolerance, the actual policy, and your ability to absorb a large expense—not on a claim that one approach always saves money.
When is paying out of pocket a reasonable choice?
Self-funding may fit an owner who can consistently set aside money, has accessible savings for unexpected care, and is willing to accept the possibility of paying the full cost of a large bill. It avoids insurance premiums, but that money is not automatically saved unless you reserve it for care. If a bill exceeds the available savings, the remaining cost does not transfer to an insurer.
Also popular on Amazon
- SYMBIOTIC DIGESTIVE ECOSYSTEM: Our dog probiotics build a 4-way digestive ecosystem: Digestive enzymes pre-break nutrients for easy absorption, while probiotics + prebiotics balance and nourish gut flora. Pumpkin helps dogs with a sensitive stomach maintain regular bowel movements. These layers go beyond ordinary probiotics, turning every meal into steady nourishment, digestive ease, and enduring energy*—so your dog stays balanced and full of life.
- TRIPLE IMMUNE SUPPORT: Gut health drives immunity, and our probiotics for dogs target it. Probiotics help maintain a balanced gut microbiome and support mucosal immunity, while plant antioxidants* (Rosemary & Green Tea) and natural Vitamin E help protect immune cells from daily wear and tear. Formulated for triple immune support - helping your dog stay vibrant and ready for everyday adventures.
- DUAL-ACTION SKIN & COAT NOURISH: True skin and coat health starts from within. Gut and immune support work in sync with Salmon and Flaxseed Oils (Omega-3 & 6) to nourish skin and coat from the inside out. This dual-action care promotes a soft, shiny, and glossy coat you’ll love to touch.
- PURE INGREDIENTS: We believe in complete ingredient integrity. Every batch of our dog probiotic chews is crafted in GMP-certified facilities using trusted, premium sources. They are free from grains, soy, and artificial additives. This commitment to safety and quality ensures a clean formula you can trust for your dog’s overall wellness.
- TASTE DOGS LOVE: Made with natural duck flavor, our probiotic chews are loved by most dogs, even picky eaters. Unlike other hard chews, these soft, easy-to-bite chews are perfect for puppies and senior dogs. They help support digestive comfort, gut balance, and skin & immune health: areas commonly affected by occasional diarrhea, seasonal allergies, itchy skin, or paw licking. A tasty daily chew your dog will love.
Consider the practical downside, not only the average outcome you hope for. If an unexpected expense would force you to borrow, delay care, or make a difficult decision about treatment, keeping all veterinary-cost risk may not match your financial situation—even if you prefer to avoid premiums. Conversely, a policy with important exclusions or limits may leave you carrying more risk than its price suggests.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.When may insurance be the better fit?
Insurance may suit an owner who wants help with some eligible high-cost care, prefers a predictable recurring premium to bearing the entire risk, and can manage the policy’s exclusions and upfront payment requirements. It is most useful to assess a policy before a condition arises, because pre-existing conditions are rarely covered; purchasing still does not bypass waiting periods or guarantee coverage for future treatment.
Free tools Windows power users keep installed
One-click scans. No signup required.
Do not choose a plan solely because it has a low premium or a high advertised reimbursement percentage. A lower premium may accompany narrower coverage or different cost sharing, while reimbursement depends on the policy’s calculation and limits. Compare the specific contract against the expenses and risks you want help with.
What does the market data say—and what does it not say?
NAPHIA’s 2026 report highlights say that its 2025 data represents approximately 99% of written pet-health-insurance premium in the United States and Canada. Its April 2025 announcement also reported industry enrollment growth: NAPHIA’s president described a 20.9% increase from 5.17 million insured pets across its sector in 2023. The association’s executive director said North American pet-insurance penetration for dogs and cats combined had reached nearly 4% by year-end 2024.
Also popular on Amazon

- COMPLETE 26-IN-1 DAILY WELLNESS FORMULA: Our advanced multivitamin for dogs is formulated to help support 26 vital nutritional areas as part of a daily routine. With essential vitamins A, C, D3, and E, these gummies help support the immune system and contribute to overall heart and brain health for dogs of all sizes.
- ADVANCED HIP AND JOINT MOBILITY SUPPORT: Formulated with Glucosamine HCl, Chondroitin, and MSM to help support cartilage health, joint flexibility, and everyday mobility — making them a great daily supplement for large breed dogs and active senior dogs.
- SKIN & COAT SUPPORT: Packed with Norwegian Salmon Oil and Biotin, our dog multivitamin helps nourish skin from within and supports a soft, glossy coat. Omega 3 fatty acids contribute to healthy skin and coat as part of a complete daily nutritional routine.
- PROBIOTICS & DIGESTIVE SUPPORT: Features a Six-Probiotic Blend (500 Million CFU) and Digestive Enzymes to help support gut health, smooth digestion, and nutrient absorption. Cranberry Powder is included as part of this comprehensive daily wellness formula.
- UNBEATABLE VALUE 250 COUNT JAR: Our 250-count jar provides lasting daily support in a delicious chicken flavor. Made in the USA in a GMP-certified facility, our soft chews are grain-free and suitable for puppies, adult, and senior dogs alike.
These figures describe industry participation, not the financial outcome for an individual owner. More insured pets or a larger insurance market does not demonstrate that insurance is cheaper than self-funding over a pet’s lifetime. The available sources do not provide a representative, matched lifetime comparison of total premiums and eligible claims for insured and uninsured pets. Treat premium averages as context, not a break-even calculation.
Bottom line: which option should you choose?
Choose insurance if the actual policy offers useful protection for risks you want to transfer and its premiums, cost sharing, exclusions, and reimbursement process fit your budget. Choose to pay out of pocket if you can fund care yourself and are comfortable retaining the full bill risk. If neither conclusion is clear, compare a current quote and the complete policy against your accessible savings and willingness to absorb an unexpectedly large expense. There is no universal winner, and the market averages cannot tell you which choice will cost less for your pet.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Frequently Asked Questions
Can I switch pet insurance plans and get coverage for a condition from my old plan?
Do not assume you can. Pre-existing conditions are rarely covered, and the new policy’s definitions and your pet’s veterinary records can affect eligibility. Ask the prospective insurer how it will treat the specific condition before canceling existing coverage.
Can I use pet insurance at any veterinarian?
The available sources do not establish a universal provider-network rule; policies and payment arrangements can vary. Before enrolling, ask the insurer whether your preferred clinic is eligible and whether any direct-payment option requires the clinic’s participation.
Does pet insurance cover dental care?
Coverage depends on the policy’s definitions, exclusions, and benefit terms, so the plan name alone is not enough to determine it. Check the contract for the specific dental treatment and whether routine or preventive dental services are treated differently from illness or injury care.
Leave a Reply