
Some links on this page are affiliate links: if you buy through them we may earn a commission, at no extra cost to you.
If your pet insurance claim is rejected, do not assume the decision is final. Read the denial letter, identify the exact exclusion, limit, waiting-period rule or evidence problem the insurer relied on, then request a formal internal review before the deadline in your policy or notice. Build the appeal around the contract wording and a complete veterinary record, with your veterinarian addressing the insurer’s stated reason. If the insurer does not put things right, escalate through the route for your location: the Financial Ombudsman Service in the UK after the insurer has had the required opportunity to respond, or your state insurance department in the United States. The process, deadlines and remedies differ by policy and jurisdiction, so keep every document and communication.
What should I do first after a pet insurance claim is rejected?
Start with the insurer’s written decision, not a phone summary. Your first objective is to discover precisely why the claim failed and which part of the policy the insurer says supports that outcome.


As an Amazon Associate I earn from qualifying purchases.
- Save the complete denial notice. Keep the letter or email, attachments, claim number, date issued and any explanation of appeal rights.
- Mark the contractual reason. Look for wording about a pre-existing condition, symptoms during a waiting period, a treatment time limit, dental or bilateral-condition exclusion, aggression exclusion, misrepresentation, reasonable-care requirement, excess, co-payment, annual or lifetime limit, or a change at renewal.
- Compare the reason with the correct policy version. Use the schedule, full wording, endorsements and renewal documents that applied on the date of treatment. A later renewal document may not describe the cover in force when the veterinary care occurred.
- Ask for anything missing. If the explanation is vague, request the exact clause, the facts the claims assessor relied on and a copy of relevant claims notes or medical-review findings.
Admiral says it will explain why a claim was unsuccessful. A decision that simply says “not covered” without identifying the relevant term is difficult to assess, so ask for a fuller written explanation before preparing your appeal.
What if the insurer’s explanation is only verbal?
Send a short follow-up message confirming what you were told and ask the insurer to correct any misunderstanding in writing. Written reasons create a record for an internal appeal and, if necessary, a later complaint to a regulator or ombudsman.
Popular on Amazon
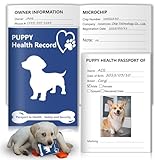
- Product Include:When you choose our dog vaccines records tracker, you'll receive one notebook.This 12-page puppy health journal has 8 dedicated pages for tracking your pup’s health, vet visits, and key details, with 4 blank pages at the end for jotting down extra notes, pet-related info, or anything else you want to record.
- Ideal Size for Record Keeping:Each dog vaccine record book measures 5x3.5 inches folded; 5x7 inches unfolded, allowing for easy portability and storage.These handy health records notebook for dogs with double sided printing, featuring enough space for all your pets important information,plus, it has dedicated spots for sticking on vaccine stickers and adding cute puppy photos.They offer a stylish and organized approach to pet health documentation, a must have addition to your pet supplies.
- Premium Quality: The puppy health record tracker’s cover features 300gsm coated paper with vibrant full-color printing and a protective laminate finish. Inside, 100gsm high-quality offset paper pages are durable and ink-resistant, ensuring no bleeding from pens or markers—so your records stay neat and easy to read.
- Effortlessly Track Vaccinations and More:The canine health record booklets pages include:owner and puppy information,medical history and hospitalizations,vaccination record and sticker,dog service providers,fecal examinations and de-worming,heartworm screening, prevention and treatment etc.This record keeping tool will ensure every important detail is accounted for and make this task easy, organized, and straightforward.Add this essential tool to your pet supplies for a happier, healthier pet.
- Essential for Pet Owners:Designed for veterinary clinics and pet owners, these puppy vaccination record books make tracking key health details—like shots, checkups—simple and organized. When you’re away and leave your pup with a sitter or family, the dog medical record and vaccine book serves as a quick reference for their medical history. Plus, dedicated sections for photos, physical markings, and ID info prepare you for emergencies, helping you recover your friend quickly if they get lost.
How do I appeal a rejected pet insurance claim?
Use the insurer’s formal review or appeal process and follow the deadline stated in the policy or denial notice. Procedures are insurer-specific; Embrace, for example, describes a 60-day appeal window, says an appeal may take 15 or 30 business days depending on the policy version, and allows a second appeal within 30 days when the first is unsuccessful.
- Confirm the deadline and submission method. Check whether the insurer requires an online form, email, post or a particular department. Ask for confirmation if the notice gives conflicting dates.
- Request the outcome you want. State whether you want the denial overturned, a specified covered amount paid, or a corrected calculation of the benefit after the excess or co-payment.
- Build a dated chronology. List the first symptom, each consultation, diagnostic test, treatment, invoice, claim submission and insurer communication. Keep dates consistent with the veterinary record.
- Answer the stated reason point by point. Quote the relevant policy wording, explain the factual correction and identify the document or veterinarian statement proving it.
- Attach an indexed evidence file. Name files clearly and refer to them in the letter so the reviewer can find each item.
- Ask for a written final response. Request the insurer’s final position, the contractual basis for it and information about the next complaint or escalation route.
What should a veterinarian’s letter say?
The letter should address the denial reason directly rather than merely confirm that treatment occurred. Depending on the dispute, ask the veterinarian to state when signs first appeared, whether the condition is clinically linked to an earlier symptom, what the diagnosis was based on, and whether the treatment was medically necessary. The clinician should distinguish documented facts from opinions and identify supporting records, test results or imaging.
Free tools Windows power users keep installed
One-click scans. No signup required.
Can I appeal a partial payment?
Yes. Treat an underpayment like a denial of the disputed portion. Recalculate the amount using the policy’s benefit limit, excess, co-payment and any sub-limit, then explain why the insurer’s calculation is wrong and request payment of the specific balance.
What documents and evidence should be in the appeal?
A strong appeal lets a reviewer verify coverage without repeatedly asking you for basic records. The Financial Ombudsman Service identifies the following categories as useful evidence.
- Policy schedule, full wording, endorsements, renewal notices and any amendment that applied when the treatment occurred.
- Denial letter, claim number, completed claim form, correspondence, call notes and any internal review form.
- Itemized veterinary invoices, receipts or other proof of payment.
- Clinical notes, referral letters and the pet’s complete medical history, including records from earlier practices where relevant.
- Diagnostic reports, laboratory results, radiographs, scans and treatment plans.
- A veterinarian letter that responds to each reason in the denial.
- A dated timeline of symptoms, consultations, treatment, communications and submissions.
- A concise appeal letter stating the correction requested and the amount you believe is covered.
Do not send only a paid invoice. An invoice proves that money was charged; it usually does not establish when symptoms began, whether a condition was pre-existing or whether an exclusion applies. Ask the practice for legible, complete records and check that names, dates and the pet’s identification match the claim.
Also popular on Amazon

- All-in-one pet care tracking: vaccinations, vet visits, medical exams, medications and more
- Easy access to pet’s health info: stay organized and on top of your pet's health
- Ample writing space: never run out of space; designed to last entire life of pet
- High-quality materials: durable and elegant design for long-lasting use
- Portable size: convenient A5 size, perfect for on-the-go; practical for vet visits and storage
How should I organize a large evidence file?
Use a simple index: 1) appeal letter, 2) policy documents, 3) denial, 4) chronology, 5) veterinary records, 6) diagnostics, 7) invoices and payment proof, and 8) prior correspondence. Combine related pages into clearly named PDF files where allowed, retain the originals and keep a copy of exactly what you submitted. A pet medical records organizer can help keep policy and veterinary documents together, but it does not replace the insurer’s required form or records.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Why are pet insurance claims rejected?
Most disputes turn on the contract’s definition of the condition, the timing of symptoms, a coverage limit or a missing fact. The same diagnosis can produce different outcomes under different policy wording.
Pre-existing conditions and waiting periods
An insurer may say the pet had symptoms before cover began or during an initial waiting period. Compare the policy’s definition of “pre-existing” with the first documented symptom, not merely the date of diagnosis. Ask the veterinarian to distinguish an isolated earlier sign from the later condition if that distinction is medically supportable.
Time limits and treatment windows
Some policies restrict how long a condition remains claimable or impose a deadline for submitting treatment. Check both the benefit period and the notification rule. A claim can be rejected even when the treatment itself is medically covered if it was submitted outside a contractual time limit.
Dental, bilateral and aggression exclusions
Dental work may be excluded except in narrowly defined accidental-injury circumstances. Bilateral-condition clauses can treat a problem affecting one side as related to a condition on the other side, while aggression exclusions may apply to injury or liability claims involving a pet’s behavior. The exact wording and medical facts matter; ask the veterinarian to explain whether the current problem is the same condition, a related condition or an unrelated event.
Also popular on Amazon
Misrepresentation and reasonable-care clauses
An insurer may allege that information was omitted or that reasonable care was not taken. Request the specific statement it says was inaccurate, when it was made and why it affected coverage. Provide the original proposal answers, veterinary records and any explanation showing what you knew at the time.
Excesses, co-payments and policy limits
A payment can be reduced rather than completely refused because of a fixed excess, percentage co-payment, annual limit, per-condition limit or sub-limit. Rework the calculation from the itemized invoice and policy schedule. Ask the insurer to show each deduction so you can challenge an arithmetic or classification error separately from a coverage dispute.
Changes to lifetime cover at renewal
For a lifetime or lifelong policy, compare each renewal schedule with the original promise of cover. Check whether basic cover, exclusions, limits or co-payments changed and whether the insurer offered a fair continuation option. The Financial Ombudsman Service notes that a replacement policy is unlikely to cover conditions the pet already has, so switching policies after a problem appears can leave that condition excluded.
What should my appeal letter include?
Keep the letter factual and short enough for a claims reviewer to follow. A useful structure is:
- Identify the policy, claim number, pet and treatment dates.
- Quote or paraphrase the insurer’s stated reason.
- State why that reason does not apply, using the relevant clause and documented facts.
- Refer to each attachment by number.
- Request a specific remedy and a written final response.
Subject: Formal appeal – claim [claim number], [pet’s name]

I appeal the decision dated [date], which says [insurer’s reason].

The policy wording at [section/page] provides [relevant cover or definition].
The attached chronology and veterinary letter show [key factual correction].
Please review the decision and [overturn the denial/pay £ or $ amount/correct the calculation].

Attachments: 1. policy schedule; 2. denial; 3. chronology; 4. veterinary records;
5. diagnostic reports; 6. itemized invoices and payment proof.

Please send your written final response and explain any remaining refusal by reference
 to the policy wording.
Remove statements you cannot support and do not speculate about a diagnosis. If a record is incomplete, say so and explain when you requested it.
Also popular on Amazon
What are the UK deadlines and escalation steps?
In the UK, complain to the insurer first. The Financial Conduct Authority says firms generally must provide a written outcome within eight weeks. If eight weeks pass without a final response, or the final response is unsatisfactory, you can approach the Financial Ombudsman Service, provided the complaint meets its eligibility rules.
- Submit the insurer’s formal complaint or appeal and keep proof of delivery.
- Cooperate with requests for records while preserving the original deadline.
- When the insurer sends its final response, check the instructions and time limit for referring the matter to the Financial Ombudsman Service.
- If eight weeks pass without a final response, ask the Ombudsman whether you can refer the complaint at that point.
The FCA rulebook says an insurer must handle claims promptly and fairly. The Ombudsman describes its service as free and easy to use. It can consider the evidence, policy wording and fairness of the insurer’s decision, but you should still meet every referral deadline in the final-response letter.
What are the US deadlines and escalation steps?
There is no single US deadline equivalent to the UK eight-week process. Policy terms, state law and regulator procedures vary, so read the policy and contact the insurance department in the state that regulates the policy.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →- Complete the insurer’s internal appeal or complaint process if the policy requires it.
- Ask the insurer for its final written position and retain the claim file.
- Identify the state insurance department responsible for the policy and follow its complaint form and submission rules.
- Submit the denial, policy, appeal, veterinary evidence and correspondence in the format requested.
Tennessee’s regulator accepts complaints about wrongful denials for qualifying policies written in Tennessee and provides online, mail and fax submission options. That route does not automatically apply to a policy issued or regulated elsewhere. A state department may review compliance with insurance requirements, while the insurer’s contract and the state’s procedures determine what relief is available.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Should I use an insurer appeal or an ombudsman or regulator?
Use the internal appeal first unless your policy or local rules clearly provide another route. It is usually the fastest way to correct a missing document or factual error; external escalation is the next step when the insurer stands by its decision or fails to respond.
Also popular on Amazon
| Route | Who can use it | When to file | Evidence | Cost and outcome |
|---|---|---|---|---|
| Insurer internal appeal | Policyholder covered by the insurer’s appeal process | Deadline in the policy or denial notice; Embrace gives a 60-day example | Policy, denial, claim file, veterinary records and targeted clinician letter | Usually no separate fee; insurer issues a revised or final decision |
| Financial Ombudsman Service | Eligible UK consumers after the insurer has had the first opportunity to resolve the complaint | After an unsatisfactory final response or, generally, eight weeks without one | Complete complaint file, policy wording, medical evidence and chronology | Service is free; eligibility and referral deadlines apply |
| State insurance department | Policyholders whose policy falls under that state’s jurisdiction | State and policy procedures vary; check before filing | Denial, policy, appeal, correspondence and supporting records | Fees and available remedies vary by state; follow the regulator’s instructions |
Do not send an external complaint while an internal deadline is expiring without also protecting your appeal rights. Tell the insurer that you are appealing and ask whether the external complaint changes any contractual deadline.
What mistakes can weaken an appeal?
- Submitting only a general statement that the claim is “unfair” without addressing the cited clause.
- Using a policy schedule from the wrong renewal year.
- Leaving gaps in the medical history that allow the insurer to infer an earlier symptom.
- Asking a veterinarian to argue coverage instead of explaining the medical facts.
- Missing an appeal or Ombudsman referral deadline while waiting for records.
- Sending originals without keeping a complete copy and proof of delivery.
- Accepting a telephone explanation instead of requesting a written final position.
If a record is delayed, submit the appeal on time with an explanation and ask for permission to add the document. Never alter a veterinary record; provide a correction or supplementary letter that identifies the date and reason for the clarification.
How can I tell whether pursuing the dispute is worthwhile?
Proceed when you can identify a plausible coverage term and a document that contradicts the insurer’s factual assumption or calculation. An appeal is less likely to succeed when the policy clearly excludes the treatment, the condition falls outside an unambiguous limit or the claim was submitted outside a mandatory deadline with no contractual exception.
Separate the issues. You may accept that one invoice item is excluded while still challenging a waiting-period decision on another item. Ask for the undisputed amount to be paid and identify only the balance that remains in dispute.
Frequently Asked Questions
Can I add veterinary records after I submit my appeal?
Usually you can ask the insurer to accept supplementary evidence, but the policy may set a closing date for an appeal. Submit the appeal on time, explain which record is pending, and request written confirmation that the reviewer will consider it when received.
What if my pet changed insurers after the treatment?
Use the policy that was active when the symptoms, accident or treatment covered by the claim occurred. A replacement policy generally will not cover a condition the pet already had, so include both policies and renewal dates if responsibility is disputed.
Recommended Free Tools
Can a regulator force an insurer to pay my claim?
That depends on the regulator and the law governing the policy. A regulator may examine whether the insurer followed insurance requirements, while a contractual dispute may need the insurer’s complaint process, an ombudsman or another legal remedy.
What should I do if the insurer says my veterinarian’s notes are incomplete?
Ask the practice for the full contemporaneous record, including referral notes, test reports and medication history. If the record contains an error, request a dated supplementary statement rather than changing the original entry, and explain the correction in your appeal.
Leave a Reply